How to Improve Your Personal Credit Score
Quick Tips To Improve Your Personal Credit Score
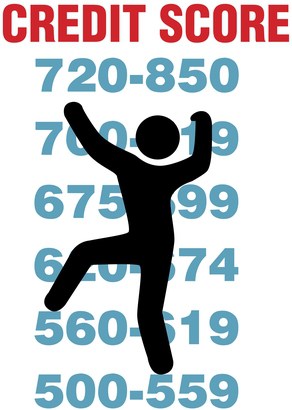
 Your personal credit score is a figure that illustrates how creditworthy you are. It’s a crucial factor that lenders consider when determining whether to grant you a loan, and it may also have an impact on your ability to obtain insurance, find housing, or even land a job. Your personal credit score is based on your credit history, which contains details about the loans and debts you’ve paid back as well as how long those payments have been past due. This article will help you improve your personal credit score.
With interest rates on the rise. Everyone is looking to refinance as quickly as possible. You must improve your credit score before you apply for your refinance. Even if you just want to apply for a personal loan or a new credit card. Improve your chances not just of approval but of getting the best rate by increasing your credit score. Let’s discuss practical pointers on how you can use your credit score to get easy approval and enjoy better rates and terms:
Start by Checking Your Credit Report
Obtain a copy credit report from all 3 major bureaus. Be sure to order a copy of your credit report from each of the three major credit bureaus (Equifax, TransUnion, Experian). Take note that each credit bureau works on its own so the report you get from one bureau may be different from the other two.
Clean up your credit report. Check your credit report for possible errors or unauthorized charges. You don’t have to pay charges if they’re not yours. You can dispute incorrect charges in your account by sending a letter to the creditor involved and the credit bureau that issued your report. This way, an investigation can take place immediately to have the errors corrected.
Keep a Low Debt-to-Income Ratio
 Work on improving your debt to income-ratio. How much of your credit limit has been used? Financial experts recommend not using up more than 50% of your limit. But what if you have a high credit-to-debt ratio? You can call your bank or credit card issuer and request a higher credit line. Of course, the easiest way to free up your credit limit is to pay off your existing charges.
Insiders tip: Sometimes when we are working with a business to get the financing, the owner has nearly maxed out his / her personal credit cards to run their business. If they can’t pay it down, we ask them to call and get a credit line increase! That way it looks like they are using a smaller percentage of their available credit and will give their credit report a quick credit score boost!
Pay off your existing bills to improve your personal credit score
Raise your credit score the fast way by paying off all unpaid charges. What if this isn’t possible? Speak with your creditors and arrange for new repayment terms. Be open about your financial situation and explain why you’re asking for payment modifications. Most lenders are willing to cooperate especially if a customer is experiencing a financial crisis due to circumstances such as divorce, loss of job, death, or illness.
Pay off your high-rate debts first. Pay your debt with the highest rate of interest first and work your way down. This is the best strategy to deal with multiple debts if you can’t pay off all debts at once.
Avoid new debts. Stay away from incurring new debts while you’re still under repayment. Focus on paying off your existing debts and use your monthly income to pay your creditors.
Improving your credit score can be a daunting task. But by following the above tips you will be well on your way to improving your score. Just don’t expect it to happen overnight. For instance, when you pay down your credit card it may not be reflected that month on your credit report. Depending on when your creditor reports to the bureaus. You may have paid it off a few days AFTER they reported, so it won’t be reflected that month, but it should be the following month.
Don’t Max Out Your Credit Cards to improve your personal credit score
Don’t use your credit cards to the limit if you want to keep your credit score high. Although it might seem obvious, many people disregard the consequences when they engage in this behavior.
Your credit utilization ratio rises as you reach the credit limit on your cards. Your total credit card balance divided by your total credit limit yields this percentage. A high ratio can hurt your credit score, so it’s essential to keep it below 30%.
Don’t Apply for Too Many Credit Cards at Once
Applying for too many credit cards at once will actually lower your credit score rather than raise it. Lenders look at your credit score when you apply for a new credit card to see whether you are a good risk for a new account. Too many recent queries on your credit record give the impression that you are thirsty for additional credit and raise the possibility that you may default on current loans. Due to this, the lender can decide to reject your application or approve it but charge you a higher interest rate.
 Try not to apply for more than one or two new credit cards in a six-month period if you want to raise your credit score. The lenders will have ample time to update your credit score and establish that you are not a high-risk borrower if you do this. Additionally, it’s important to maintain a modest debt balance and pay your obligations on time every single time.
Monitor Your Credit Score
By keeping a close eye on it and taking efforts to strengthen your credit history, you can raise your credit score. AnnualCreditReport.com offers free access to your credit score. You can access your credit report from each of the three major credit reporting companies, Experian, Equifax, and TransUnion, on this website.
Your personal credit score is a key indicator of your financial health. It reflects your credit history, payment history, and utilization of credit. A good personal credit score can help you get approved for loans and other forms of financing, and can also improve your chances of getting a good job.
Finally, by applying the advice in this article, you can try to raise your own credit score. This will make it simpler for you to get finance when you need it, and it can also lead to lower interest rates on any loans you already have. Take the required actions to raise your credit score because it’s crucial to have one.